

Auto Financing That Fits Your Next Chevy
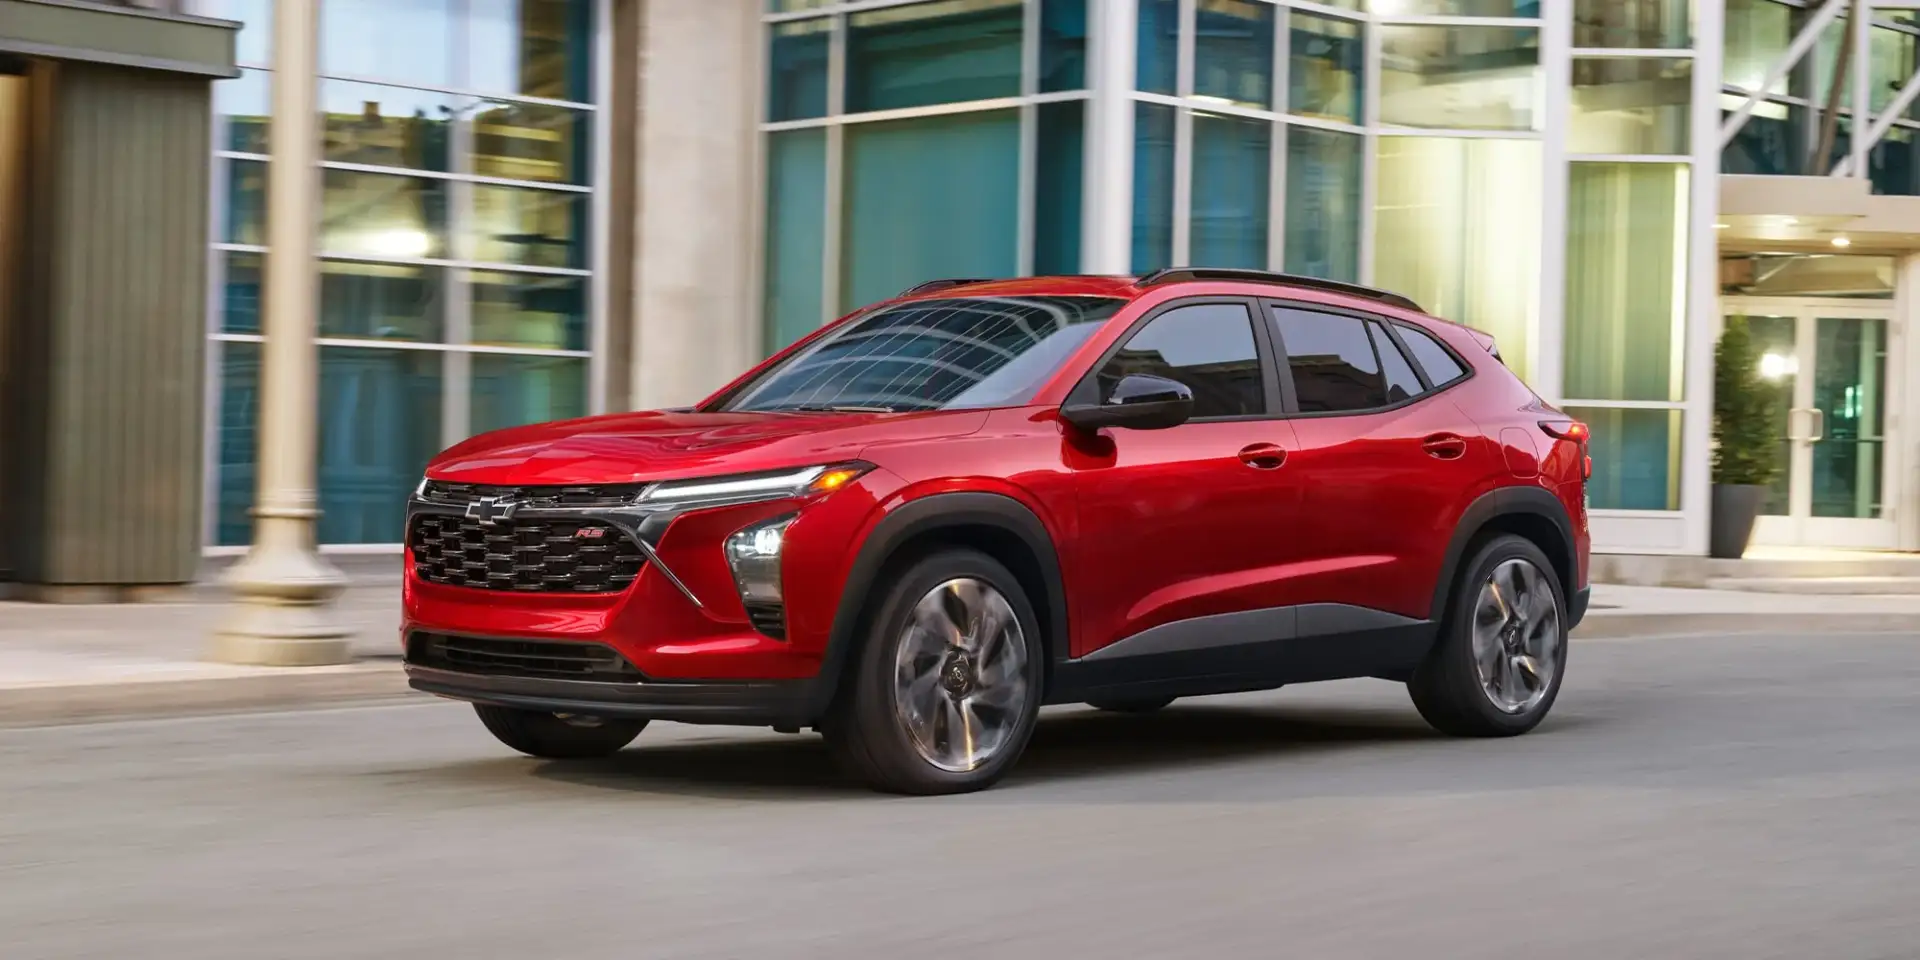
The right vehicle should fit more than your driveway. It should fit your daily routine, your family’s needs, and your monthly budget. Auto financing is how many shoppers make that balance work, whether they are considering a Silverado for towing around Lake County, an Equinox for weekday commutes, or a CarBravo certified used vehicle that delivers added value.
Financing does not need to feel mysterious or high-pressure. When you understand the pieces that shape a loan, you can compare vehicles and payment options with more confidence. The goal is not simply to reach a monthly payment. It is to choose a vehicle and loan structure you will feel good about long after you leave the dealership.
How Auto Financing Works
Auto financing allows you to borrow money to purchase a vehicle and repay that amount over an agreed term. Your monthly payment generally includes the amount financed, plus interest and any applicable taxes or fees. A lender reviews your application, then offers terms based on factors such as credit history, income, the vehicle selected, the down payment, and the length of the loan.
The amount you finance is not always the same as the vehicle’s listed price. A trade-in, cash down payment, vehicle protection products, taxes, registration costs, and any remaining loan balance on your current vehicle can all affect the final amount. That is why a full, itemized discussion is more useful than focusing on one number alone.
At a Chevrolet dealership, the finance team can help submit your application to available lending sources and explain the options you receive. You remain in control of the decision. Ask questions, review the details, and take the time you need to understand how each choice changes the overall picture.
The Four Choices That Shape Your Payment
A payment is usually influenced most by the vehicle price, down payment or trade equity, annual percentage rate, and loan term. These pieces work together, so changing one can affect the others.
A larger down payment reduces the amount borrowed. That may lower the monthly payment and can help build equity in the vehicle sooner. Trade-in value can serve a similar purpose, especially if your current vehicle is paid off or worth more than its remaining payoff amount.
Your interest rate affects the cost of borrowing. Strong credit may open the door to more favorable terms, but buyers with limited credit history or past credit challenges may still have options. The best approach is to be accurate on your application and realistic about what payment feels sustainable alongside your other household expenses.
The loan term is another key decision. A longer term can lower the monthly payment by spreading repayment across more months. The trade-off is that you may pay more interest over the life of the loan and could build equity more slowly. A shorter term often means a higher monthly payment, but less total interest and a faster path to ownership. Neither choice is automatically right for every household.
Why the Lowest Payment Is Not Always the Best Deal
A low monthly payment can be helpful, especially for a growing family or a shopper balancing several expenses. Still, it should not be the only comparison point. Consider how long you plan to keep the vehicle, how many miles you expect to drive, and whether you may want to trade it in before the loan ends.
For example, a Gurnee driver who plans to keep a Traverse for many years may prioritize a repayment plan that builds equity steadily. A shopper who changes vehicles more often may pay closer attention to estimated trade-in value and the remaining balance over time. Looking at the full loan details helps prevent surprises later.
Prepare for Auto Financing Before You Shop
A little preparation can make the dealership visit easier and more productive. Start by reviewing your credit report for errors and checking your monthly budget. Think beyond the vehicle payment to include insurance, fuel or charging, maintenance, registration, and everyday ownership costs.
It also helps to gather documents you may need for a credit application. Common examples include a valid driver’s license, proof of income, proof of residence, insurance information, and details about a trade-in. Requirements can vary by lender and personal situation, so the finance team can tell you exactly what is needed.
If you have a trade-in, bring it in for an appraisal rather than relying only on an online estimate. Vehicle condition, mileage, equipment, local demand, and market changes all influence its value. Be sure to share whether there is an existing loan on the vehicle. A clear payoff figure is essential when comparing your options.
Pre-approval can also be useful for some shoppers. It gives you an early sense of what a lender may offer and helps you establish a budget range. Even then, compare the complete terms available through the dealership. A familiar local team can help you weigh lender offers, manufacturer programs when available, and the specifics of the vehicle you choose.
New, Used, or CarBravo Certified Used?
Your financing approach may change depending on whether you choose a new Chevrolet, a pre-owned vehicle, or a CarBravo certified used model. New vehicles may offer current technology, full factory coverage, and, at times, special financing programs for qualified buyers. Availability and qualification requirements can change, so it is always worth asking about current offers rather than assuming they apply.
A used vehicle can be a smart choice for shoppers focused on overall value or looking for a particular trim, capability, or feature set. Financing terms on used vehicles can differ from new-vehicle terms based on age, mileage, and lender guidelines.
CarBravo certified used vehicles can appeal to buyers who want additional confidence in a pre-owned purchase. They offer a middle ground for shoppers comparing a newer vehicle experience with used-vehicle value. If you are deciding between a new Equinox and a CarBravo certified used SUV, compare not just the payment, but warranty coverage, expected ownership time, features, and condition.
Financing an EV or Truck: Match the Loan to Your Life
The vehicle you choose should drive the financing conversation. An EV-curious buyer comparing the Equinox EV, Blazer EV, or Silverado EV may want to think through home charging access, anticipated driving range, and possible incentive eligibility. Some incentives have specific eligibility rules, and those rules can change. A dealership team can help you understand what questions to ask before making a decision.
Truck shoppers should consider the capability they will actually use. A Silverado or Colorado may be the right partner for a boat, trailer, jobsite equipment, or weekend projects. But towing needs, cab configuration, bed length, and available equipment can affect the vehicle you select and the amount financed. Choosing enough truck for the job matters, but so does avoiding features you may not need.
For many families in Mundelein, Vernon Hills, Grayslake, and Waukegan, an SUV is about flexibility. Third-row space, cargo room, all-weather confidence, and safety technology may carry more weight than maximum towing. Discussing how you use a vehicle helps narrow the selection before you decide on financing.
Questions Worth Asking in the Finance Office
A welcoming finance conversation should leave you clearer, not more confused. Ask for the annual percentage rate, loan term, estimated monthly payment, total amount financed, and whether there is a prepayment penalty. Ask how your trade-in and remaining payoff are being handled. If you are considering optional protection products, ask what each one covers, how long it lasts, and whether it fits your ownership plans.
You can also ask how different down payment amounts or terms would change your payment. Seeing two or three realistic scenarios is often more helpful than trying to guess the best route on your own. There is no need to rush past a question just because paperwork is involved.
Take the Next Step With Confidence
A vehicle purchase is personal, and the financing should reflect that. Whether you are shopping for a family-ready Traverse, a capable Silverado, or an efficient Equinox EV, Libertyville Chevrolet is ready to help you compare the options in a straightforward, family-focused setting. Browse new and used inventory, value your trade, or begin a finance application when you are ready – then let a team member help turn the details into a plan that works for you.
Frequently Asked Questions
Can I apply for Chevy financing online before visiting the dealership?
Yes. Libertyville Chevrolet offers an online finance application, so you can share your information before you visit. Applying early can help the finance team prepare options based on your credit profile and the vehicle you are considering. You still review every term in person and decide whether a loan fits your budget before signing anything.
Does a dealership credit application hurt my credit score?
A credit application usually leads to a hard inquiry, which may cause a small, temporary dip in your score. Credit scoring models often treat several auto loan inquiries made within a short shopping window as a single inquiry. Shopping for your rate within a focused period, then choosing a loan, helps limit the effect while you compare options.
Is it better to finance through the dealership or my own bank?
Either can work, and comparing both is smart. A bank or credit union pre-approval gives you a reference point. A dealership like Libertyville Chevrolet can submit your application to several lenders and may have access to Chevrolet programs for qualified buyers. Compare the APR, term and total amount financed on each offer, not just the monthly payment.
What insurance do I need when I finance a car in Illinois?
Illinois requires liability insurance on every registered vehicle, and lenders typically require comprehensive and collision coverage until the loan is paid off. Some buyers also consider gap coverage, which can help if the vehicle is totaled while you owe more than it is worth. Get insurance quotes on the specific Chevrolet you are considering so your full monthly budget is clear.
0 comment(s) so far on Auto Financing That Fits Your Next Chevy