

How to Finance a Chevy for Your Next Drive
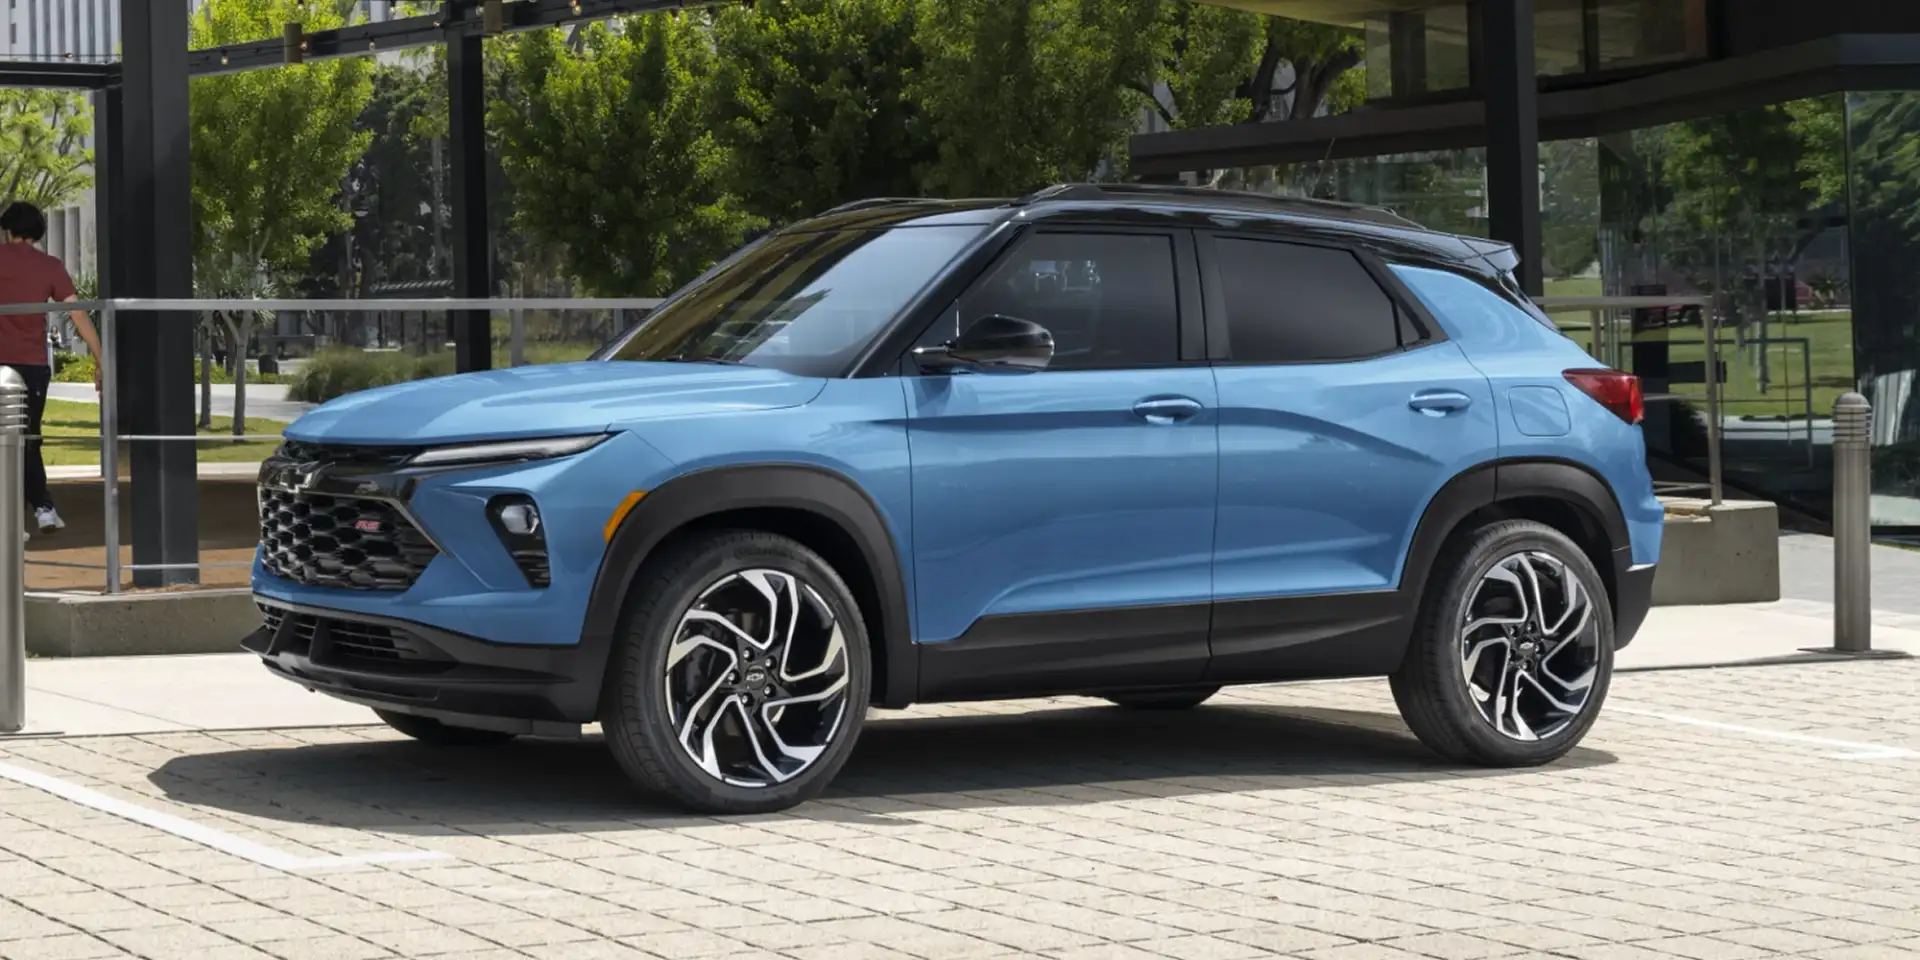
The right way to finance a Chevy is not to start with a monthly payment alone. It is to choose a vehicle, loan structure, and ownership plan that make sense together. Whether you are commuting from Gurnee, loading up a family in Grayslake, or comparing truck capability around McHenry County, a little preparation can make the process feel much more straightforward.
A Chevrolet can serve very different needs. A Silverado may be a work partner and weekend tow vehicle. An Equinox can be an easy-to-park daily driver. A Traverse may be the answer to a growing family, while an Equinox EV or Blazer EV can appeal to drivers ready to reduce gasoline stops. Financing should reflect how long you expect to keep that vehicle, how you plan to use it, and what comfortably fits your household budget.
Start With the Full Cost of Ownership
Before selecting a loan term, consider the expenses that come with vehicle ownership beyond the payment. Insurance, fuel or charging, maintenance, registration, and available warranty coverage all belong in the conversation. A lower payment on paper is helpful only if the complete monthly picture remains comfortable.
This is especially useful when comparing vehicle types. A gas-powered Equinox and an Equinox EV have different fueling routines and operating considerations. A Silverado 1500 and Colorado may both handle truck duty, but the right choice depends on passenger needs, cargo requirements, towing expectations, and day-to-day driving. The most affordable vehicle is not always the one with the smallest payment. It is the one that suits your real life without asking you to compromise in ways that matter.
If you are replacing a current vehicle, get a clear sense of its trade-in value early. A trade-in can reduce the amount you need to finance, but you should also know whether you still owe money on it. When there is an existing payoff, the remaining balance is part of the financing discussion.
How to Finance a Chevy With a Clear Budget
Set a target payment range, but also decide how much you can put toward a down payment and how long you want to make payments. These three factors work together. A larger down payment generally lowers the amount financed. A longer term can reduce the monthly payment, though it may result in more interest paid over the life of the loan.
There is no one perfect term for every shopper. A driver who plans to keep a new Silverado for many years may prioritize a payment that leaves room for household goals. Someone choosing a certified used Chevrolet may prefer a shorter term to build equity sooner. The right answer depends on your budget, credit profile, vehicle choice, and long-term plans.
It helps to arrive prepared with a few practical details:
- Your expected down payment and trade-in information
- A realistic monthly payment range
- Proof of income and residence if requested
- Your current vehicle loan payoff, if applicable
- A short list of the Chevrolet models you want to compare
Having this information ready allows the financing conversation to focus on options rather than guesses.
Understand the Difference Between Payment and Loan Cost
Monthly payment matters, but it should not be the only number you review. Ask about the annual percentage rate, loan term, amount financed, and total of scheduled payments. Those details show how the loan is structured.
A very long loan term can look appealing because it lowers the payment. The trade-off is that you may pay interest for a longer period, and your equity can build more slowly. On the other hand, a shorter term can increase the payment even when it reduces the total finance charge. A finance professional can walk through multiple structures so you can compare them side by side.
New, Used, or CarBravo Certified Used?
The vehicle you choose shapes your financing options. New Chevrolet models can offer the latest technology, current safety features, and manufacturer-backed programs that may be available to qualified buyers. Availability changes, so it is wise to ask about current offers rather than assuming a promotion applies to every vehicle or every credit situation.
Used vehicles may appeal to shoppers who want a specific feature set, a different ownership timeline, or more choices within a preferred payment range. A CarBravo certified used Chevrolet can be a particularly appealing middle ground for buyers who want added confidence in a pre-owned vehicle. Review the vehicle history, condition, certification details, warranty coverage, and service records so you understand exactly what is included.
For some families in Lake County, the decision comes down to priorities. A new Traverse may make sense for shoppers who want the newest family-focused features. A certified used Traverse may be a strong fit for buyers who value a well-equipped SUV and want to manage the amount financed. Neither option is automatically better. The best fit is the one that aligns with your driving needs and financial comfort level.
Financing an EV Calls for a Few Extra Questions
EV-curious shoppers often compare the Equinox EV, Blazer EV, or Silverado EV with a familiar gas-powered model. Financing the vehicle works much like financing any other Chevrolet, but the ownership conversation has a few added layers.
Think about where you will charge most often, whether home charging is practical, and how your usual routes fit the vehicle’s range. If you are considering lease versus purchase, ask how each option may affect any current manufacturer incentives. Federal EV tax credits ended on September 30, 2025, and individual tax circumstances vary, so a tax professional is the right resource for personal tax guidance.
You should also compare insurance and any home-charging installation needs before finalizing a budget. For many drivers, the convenience of charging at home is a major benefit. For others, regular long-distance travel or limited charging access may point them toward a gas-powered or different electrified option.
Credit Questions Should Not Stop the Conversation
Many shoppers worry that they need perfect credit before applying for auto financing. Strong credit can help expand available terms, but it is not the only factor lenders consider. Income, debt obligations, payment history, down payment, vehicle selection, and loan amount can all play a role.
If you are rebuilding credit, be upfront about your goals. You may decide to focus on a dependable pre-owned Chevrolet, increase your down payment, or choose a payment that leaves more room in your monthly budget. Avoid stretching solely to reach a particular trim level or feature package. A vehicle you can comfortably maintain and pay for is usually the better long-term decision.
It is also smart to review your credit report before you shop. Check for errors, understand your existing obligations, and avoid taking on new debt immediately before applying if possible. These small steps can help you walk into the process with fewer surprises.
Questions Worth Asking Before You Sign
A welcoming dealership should make room for questions. Ask whether your payment includes any optional products, what warranty coverage applies, how your trade-in was evaluated, and whether there are different term options to consider. If a payment does not feel clear, ask to see the numbers explained another way.
At Libertyville Chevrolet, the goal is to help shoppers make a decision they can feel good about after they leave the lot, not just on delivery day. That means comparing the practical differences between a new Chevy, a used option, and a CarBravo certified used vehicle, then building a financing plan around your actual needs.
When you are ready, gather your trade-in details, narrow your Chevrolet shortlist, and apply for financing with your questions in hand. A thoughtful conversation now can help you drive home in a vehicle that fits your family, your work, and the roads ahead.
Frequently Asked Questions
How much should I put down when financing a Chevy?
There is no single right amount. A larger down payment lowers the amount financed and can reduce interest costs, while a smaller one keeps more cash available for emergencies. Many shoppers balance the two based on their savings and monthly budget. The finance team at Libertyville Chevrolet can show how different down payments change your payment and total cost.
Can I get pre-approved for a Chevy loan before I shop?
Yes. You can seek pre-approval from your bank or credit union, or submit an online finance application with Libertyville Chevrolet before you visit. Either gives you a sense of your budget range. Once you pick a vehicle, compare the complete terms, including APR, term and amount financed, so you can choose the offer that works best.
Can I finance a Chevy if I am self-employed?
Yes, self-employed buyers finance vehicles regularly. Lenders usually want proof of steady income, such as recent tax returns or bank statements, instead of pay stubs. Having those documents ready can speed up the process. The Libertyville Chevrolet finance team can tell you what a lender may request and help you submit a complete application.
Are there Chevrolet programs for military members, first responders or students?
Chevrolet has offered special programs for groups such as military members, first responders, educators and recent college graduates. Eligibility rules and availability change, and programs may not combine with every offer. Ask the Libertyville Chevrolet team which current programs apply to you and how they would work alongside your financing before you choose a vehicle.
0 comment(s) so far on How to Finance a Chevy for Your Next Drive